Navigating Irregular Income Credit Risks in Trinidad: A Playbook for Buying Essentials
Life in Trinidad often means dealing with an irregular income, which can make essential purchases feel like a tightrope walk. One strong month might cover everything, but the next leaves you counting every dollar while the fridge stops cooling or your glasses crack. Understanding the credit risks of irregular income in Trinidad helps you buy what you need without losing your balance.
In this playbook, we will walk you through the main risks and a simple six-step plan. You will also discover how flexible, transparent payments can transform a stressful purchase into a manageable one.
Irregular Income and Credit Risks in Trinidad: What to Watch For
The biggest challenge with irregular earnings is timing. Your repayment amounts usually stay fixed, but your income goes up and down. A plan that feels easy in a busy month can become a heavy burden in a slow one.
The Central Statistical Office of Trinidad and Tobago collects labour and monthly income data through its Continuous Sample Survey of Population and its Household Budget Survey. These sources highlight how incomes and spending vary across households. While they do not provide a national figure for those managing irregular earnings, we can focus on what you can control.
Here are the credit risks that hit hardest when your income fluctuates:
- Changing balances. Revolving credit cards and store accounts can add interest, making the true final cost unclear.
- Minimum-payment habits. If you only pay the minimum in a slow month, you could stretch out a debt far longer than you intended.
- Overlapping plans. Several payment instalments might fall due in the same weak month, creating a pile-up.
- Hidden costs. Unexpected fees can make budgeting much harder.
- Waiting too long. Delaying the purchase of a new fridge, stove, or prescription glasses can disrupt your home life, your work, and even your health.
The good news is that every one of these risks has a practical solution.
Your 6-Step Playbook for Essential Goods Budgeting
Step 1: Build a low-income month budget
Look back at your income over the last six to twelve months. Identify your weakest month and use that figure as your guide. First, list essential expenses like rent or mortgage, food, transport, utilities, and school costs. What remains is the amount you can safely commit to a payment plan.
Step 2: List every active instalment
Write down each payment plan you are currently paying, including its amount and end date. Overlap is often where financial stress begins. If your slow month is already tight, consider waiting for an existing plan to end before taking on a new one.
Step 3: Choose fixed, transparent terms
Look for clear instalment amounts, a definite end date, and no hidden fees. When you know the full cost upfront, you can compare it with your expected earnings. This is what transparent financing for income fluctuations looks like.
Step 4: Match the term to your cash flow
A longer term lowers each instalment, giving you more breathing room in a slow month. A shorter term clears the balance sooner. Choose the term that your low-income budget can comfortably handle, not the one your best month could manage.
Step 5: Check your options without risk
Ask if a provider uses a soft credit check. With CrediQ, soft credit checks do not affect your credit score , so you can explore your options with confidence.
Step 6: Keep a small buffer and ask for help early
Even setting aside $100 each month can cover an unexpected slow week. If your financial situation changes, speak to your provider early. Accessible support can make a real difference when plans need adjusting.
A Simple Example From Arima
Consider Anisa, a hairdresser in Arima. Her best months bring in $9,000, but her slow months might only bring in $4,500. Her essential bills cost $3,200, leaving her with $1,300 in a slow month. Then, her fridge breaks, and a replacement costs $6,000.
She spreads the cost over 24 months, which works out to $250 a month. That is less than 20% of what she keeps in her slowest month. She replaces the fridge right away, protects her food, and still builds a small buffer. (We use round numbers here to show the method; your own plan will depend on the retailer, the item, and your specific terms.)
How CrediQ Supports Flexible Payments With Volatile Income
We know financial stability is not one-size-fits-all, especially in Trinidad and Tobago. That is why we built Your Terms, Your Way . Our flexible payment plans range from 6 to 36 months, with clear terms, manageable instalments, and no hidden fees.
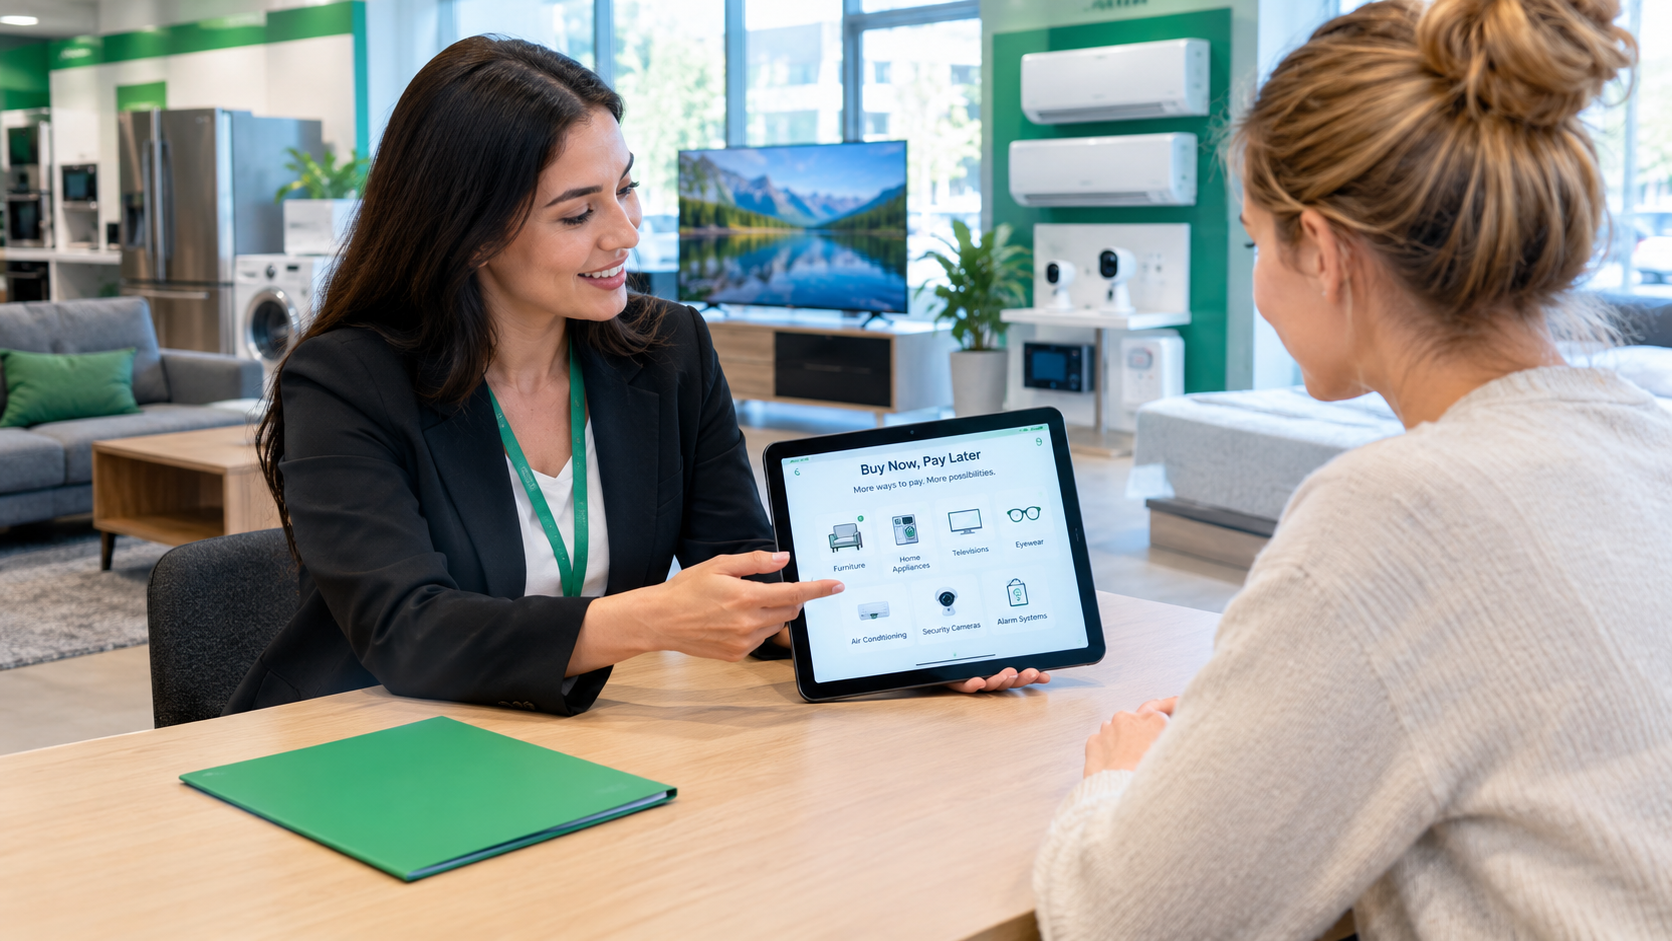
Some purchases simply cannot wait, whether it is new glasses, a fridge, a stove, or a lounge set. Retailers in towns such as San Fernando and Chaguanas can offer these higher-value items to customers who do not have the upfront cash. You can see how CrediQ works with retailers and customers to make that happen.
Responsible credit management across the Caribbean starts with borrowing for needs, not impulses, and keeping repayments within your slowest month's budget. Credit helps you afford an essential item today; it does not fix ongoing income gaps. If you frequently experience income gaps, build a savings cushion and review your budget first. That way, every plan you take on remains comfortable.
Key Takeaways for 2026
- Plan around your slowest month , not your best one.
- Choose fixed instalments, a clear end date, and no hidden fees .
- Avoid overlapping plans so one weak month does not create a financial pile-up.
- Use credit for essentials, and keep a small buffer for surprises.
- Pick a provider that offers soft credit checks and accessible support.
With these habits, stress-free essential purchases become realistic, even when your earnings change from month to month.
Ready to Plan Your Next Essential Purchase?
You deserve a payment plan that fits your real life, not just your best month. With CrediQ, you can afford what you need today, on your terms, and plan ahead with confidence. Ask us about pre-qualification and find the right plan for you: Let's talk.